Masterpiece Social

Emanuela Piller

Read the handover date clause closely

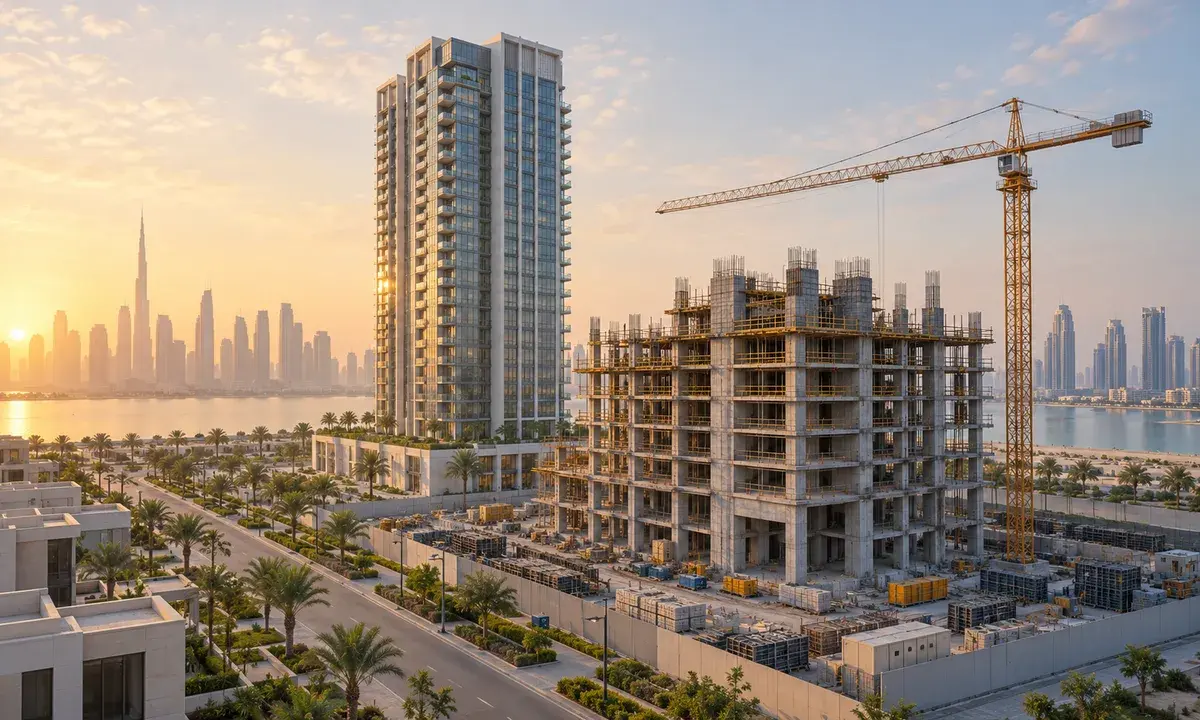
AI illustration of a UAE residential construction site, not an actual project update
The completion date in a brochure is a target; the clause in your purchase agreement is what governs. Read it for four things: the anticipated completion date, any grace period, how a delay is notified, and what the contract provides if a delay runs longer than that. Each point affects how you plan your rent, savings or move. Write the four answers on one page and keep it with the agreement. Ask the developer how progress updates are shared, and how often, so news of a change reaches you early. If the wording is unclear, ask a qualified legal adviser to explain it before you sign. Knowing the grace period in advance turns a delay notice into something you planned for rather than a surprise. Prepared by Masterpiece Property. AI-generated illustration, not a photograph of an actual property or project.

More from our team

Explore all posts
From our advisors

Read the listing agreement before you sign

The listing agreement sets the rules for how your home will be marketed, so it deserves a careful read rather than a quick signature. Check that the property details are correct, then look at the asking price, how long the agreement lasts, whether it is exclusive and what the marketing plan includes. These terms shape the next few months of your sale. Pay particular attention to two practical points: how viewings and offers will be reported to you, and how either side can end the agreement if plans change. If you own a Yas Island apartment and may reloca
Read moreAsk us on WhatsApp
From our advisors

Match the mortgage term to your working years

When a bank sets the longest term it can offer, it usually considers your age at the end of the mortgage alongside your income. Within that limit, the choice is yours. A longer term lowers the monthly payment but usually increases the total you pay over the life of the loan. A shorter term raises the monthly figure and usually reduces the total. Neither option is right for everyone. Ask the bank for two repayment schedules on the same home, one with a longer term and one shorter, and compare the monthly payment with the total repaid. Then place each sche

Read moreAsk us on WhatsApp